Post Office MIS vs PPF – Interest Rate & Tax Benefit Comparison (Complete Guide) | JobGati
Post Office Monthly Income Scheme aur PPF mein se konsa chunein? Interest, tax benefit, liquidity aur maturity – side-by-side comparison ke saath 2 minute mein decision.
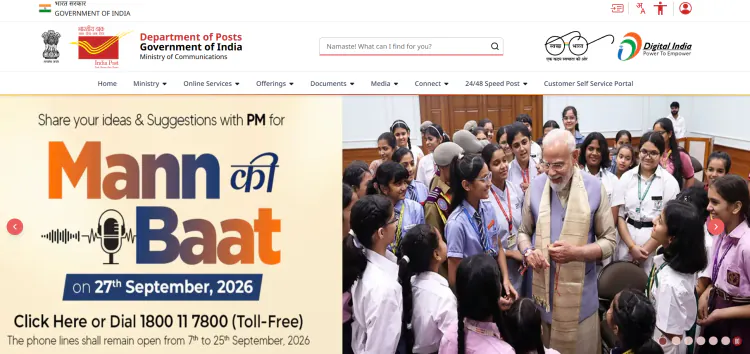
Post Office MIS vs PPF – Interest Rate & Tax Benefit Comparison (Complete Guide) | JobGati
Savings ke liye do options hamesha confused rehte hain: Post Office Monthly Income Scheme (MIS) aur Public Provident Fund (PPF). Dono safe hain, dono government-backed hain, lekin return, tax benefit aur liquidity mein dono ke apne rules hain. Is article mein main aapko dono ko side-by-side comparison mein batata hoon – aap apne age, income aur goal ke hisaab se sahi choice le sakte hain.
📌 Quick Overview
| Feature / Service | Official Details |
|---|---|
| Official Authority | Department of Post (MIS + PPF) |
| Service Type | Post Office MIS + PPF account – dono savings/income schemes |
| Key Requirements | MIS: 18+ saal + 2 witnesses; PPF: 18–60 saal + PAN |
| Fees / Charges | MIS minimum ₹5,000; PPF minimum ₹500 saal (annual), 100% per year contribution |
| Official Portal Link | indiaPost.gov.in (MIS + PPF both) |
| Processing Time | MIS account same day; PPF account 1–2 din |
📌 MIS vs PPF – Side-by-Side Comparison
| Feature | Post Office MIS | PPF |
|---|---|---|
| Account Type | Fixed income scheme (3 saal tenure) | Retirement savings account (15 saal, extendable) |
| Interest Rate | Quarterly income (rate quarterly review) – aam taur par 6.8–7.2% p.a. | Annual compound interest – aam taur par 7.0–7.1% p.a. |
| Maximum Amount | ₹9,00,000 per scheme; ₹15,00,000 per parivar | ₹1,50,000 saal Section 80C limit |
| Income Payout | Har quarter ₹X ke hisaab se paise milte hain | 15 saal ke baad maturity par lump sum; EMI bhi lo sakte hain |
| Tax Benefit | Interest income taxable hai; sirf principal 80C mein aata hai | Principal (80C) + interest + maturity teeno tax-free (EEE scheme) |
| Liquidity | 3 saal band; early closure par interest loss | 6 saal ke baad 10% tak premature withdrawal; loan facility bhi hai |
| Best For | Retired senior citizens / monthly income chahiye | Young investors / long-term tax saving |
📌 Account Kaise Kholein – Step by Step
Step 1: Post Office / e-Mudra Portal Chunein
MIS ke liye kisi bhi post office jaake scheme form bharein. PPF ke liye bank mein PPF account kholwa lein (post office bhi hai).
Step 2: Documents Upload / Submit Karein
MIS ke liye: Aadhaar + 2 witnesses + bank account details (paise se directly credit hone ke liye).
PPF ke liye: PAN + Aadhaar + bank account + photo (online bank ke liye).
Step 3: Deposit Kya Hai Karein
MIS – ₹5,000 se shuru, ₹9,00,000 tak. PPF – ₹500 se shuru, ₹1,50,000 saal tak.
Step 4: Interest / Maturity Check Karein
MIS – har quarter post office se income milta hai. PPF – annual compounding se maturity par corpus 2.5–3x ho jaata hai.
Step 5: Extension / Maturity
MIS 3 saal baad auto-mature ho jaata hai. PPF 15 saal baad maturity; 5 saal tak extend kar sakte hain.

📌 Direct Official Links
🔒 Official Source Verification: Neeche diye gaye sabhi links direct official government portals (.gov.in / .nic.in) se verified hain. JobGati par koi bhi fake ya third-party payment link provide nahi kiya jata.
| Purpose | Link |
|---|---|
| Post Office MIS + PPF (Department of Post) | indiaPost.gov.in |
💡 JobGati Pro Tip & Recommended Tools
MIS + PPF dono milakar aapka balanced retirement portfolio ban jaata hai: PPF se long-term corpus + MIS se monthly cash flow. Pehle PPF mein 15 saal ke liye invest karein, phir maturity ke aas-paas MIS mein shift karke monthly income generate karein.
Recommended Tool: PPF/SSY/NSC Maturity Calculator se maturity par aapke corpus ka estimate karein.
Related Article: Post Office Schemes KVP/SCSS/MIS Guide aur PPF Account Kaise Kholein Guide bhi padhein.
Contextual Tool Routing:
- FD Interest Calculator Tool: FD Interest Calculator se bank FD ke saath comparison karein.
- Income Tax Calculator Tool: Income Tax Calculator se 80C ke tax savings estimate karein.
❓ Frequently Asked Questions (FAQs)
Q1: Kya main dono mein ek saath invest kar sakta hoon?
A1: Haan – dono alag schemes hain, dono mein same saal invest kar sakte hain. 80C ka ₹1.5 lakh dono milakar hi aata hai.
Q2: MIS mein interest kya taxable hota hai?
A2: Haan – MIS ka income aapke income slab mein aata hai. PPF mein teeno (principal, interest, maturity) tax-free hote hain – isliye tax-saving mein PPF better hai.
Q3: MIS 3 saal se pehle khol sakta hoon?
A3: Nahi – 3 saal ke baad hi close ho sakta hai. Early closure par interest loss hota hai, lekin principal wapas milta hai.
Q4: PPF mein EMI kaise lein?
A4: PPF account open hone ke 6 saal baad partial withdrawal (10% corpus tak) allowed hai. EMI ke liye loan facility bhi hai – 50% corpus ke upar tak.
🔔 Savings & Schemes Updates Sabse Pehle Paayein: Har naya update, guide aur free tool ke liye JobGati.com ko Bookmark (Ctrl+D) zaroor karein!
⚠️ Important Disclaimer: JobGati ek swatantra shiksha portal hai. Interest rates quarterly / saharani review par vary karte hain. Koi bhi financial decision lene se pehle official sites se latest rates zaroor verify karein. JobGati.com kisi bhi investment decision ki responsibility nahi leta.
What's Your Reaction?





Comments